Buy As Is Homes in Middletown, OH: Millennium Cash Buyers serves Middletown and the surrounding area. Visit millenniumcashbuyers.com for a free quote.
TL;DR: Buying as-is homes in Middletown means purchasing properties in their current condition without seller repairs. Ohio law still requires sellers to disclose known defects even on as-is sales. Most Middletown as-is homes sell for 10–30% below comparable move-in-ready properties, and you'll need either cash, an FHA 203(k) loan, or hard money financing to close the deal.
In This Article
- What Does "As-Is" Actually Mean When Buying a Home?
- Why Are As-Is Homes Common in Middletown?
- How Much Should You Pay for an As-Is Home in Middletown?
- What Should You Inspect Before Buying an As-Is Home?
- How Do You Finance an As-Is Home Purchase in Middletown?
- Step-by-Step Process to Buy an As-Is Home in Middletown
- Finding Reliable Cash Buyers & Local Resources in Middletown
- Frequently Asked Questions About Buying As-Is Homes in Middletown
- Next Steps: Get Started Buying As-Is in Middletown
What Does "As-Is" Actually Mean When Buying a Home?
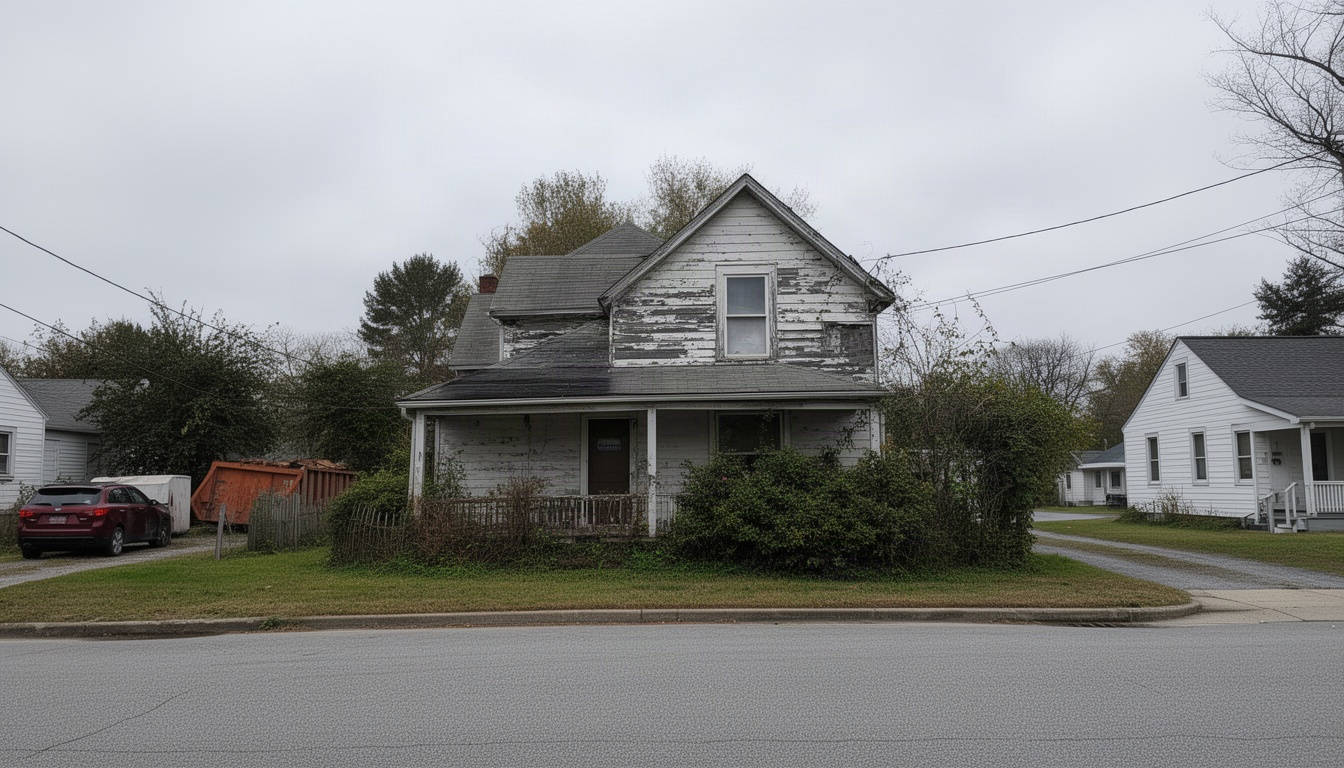
When you buy an as-is home in Middletown, you're purchasing the property exactly as it stands - roof leaks, outdated plumbing, foundation cracks, and all. The seller makes no repairs and offers no warranties on the condition of the structure or systems. However, "as-is" does not mean the seller can hide problems or lie about what they know.
Under Ohio Revised Code § 5302.30, sellers must still complete a Residential Property Disclosure Form that covers 11 categories: roof condition, foundation and basement water issues, electrical systems, plumbing, HVAC, structural defects, environmental hazards, underground storage tanks, zoning violations, HOA status, and sewer or septic systems. Fraudulent concealment of known defects exposes the seller to civil liability, even on an as-is sale. Sellers remain legally and ethically obligated to disclose major issues to buyers regardless of the as-is designation. This is a critical protection for buyers here in Middletown - it means you retain legal recourse if a seller knowingly withholds material information.
What you do waive on an as-is purchase is the seller's obligation to repair anything. You also typically waive your right to a home inspection contingency, though this is negotiable. The key distinction: as-is protects the seller from repair obligations, not from disclosure obligations. Before signing, request and carefully review the completed disclosure form line by line against your own inspection findings.
Why Are As-Is Homes Common in Middletown?
Middletown's housing stock is among the oldest in Butler County. (Ohio.gov) (Census.gov) According to the U.S. Census Bureau's 2023 American Community Survey, the median housing unit in Middletown was built in 1958 - meaning most homes are 66+ years old. Approximately 18.4% of the city's housing units were built in 1939 or earlier. This age profile creates a natural supply of properties with aging systems: galvanized plumbing, original electrical panels, roofs past their useful life, and foundations showing settlement.
Beyond age, several seller motivations drive as-is listings in our community. Estate sales represent a significant portion - when heirs inherit a property and want a quick sale without investing in repairs, they list as-is. Foreclosures and bank-owned properties are sold as-is by default. Relocation situations, where sellers need to move quickly for work, also generate as-is inventory. Additionally, some owner-occupants facing financial hardship or health issues simply cannot afford repairs and choose to pass that burden to the buyer through a lower price. Butler County foreclosure activity sustains above-average distressed inventory in Middletown's ZIP codes 45042 and 45044. This foreclosure activity, combined with the age of the housing stock, means as-is listings concentrate in neighborhoods near Central Avenue and Yankee Road, where pre-1970 homes dominate. If you're shopping in Middletown, expect to encounter as-is properties regularly - they're a normal part of our local market.
How Much Should You Pay for an As-Is Home in Middletown?
Pricing an as-is home requires a disciplined formula. The most widely used approach among investors is the 70% rule: Maximum Allowable Offer = (After-Repair Value × 0.70) − Estimated Repairs. This ensures you build in enough margin for profit (if you're an investor) or equity cushion (if you're an owner-occupant).
Here's a concrete example: Suppose a comparable move-in-ready home in Middletown sells for $175,000 (the after-repair value). Your inspection reveals $30,000 in needed repairs: a roof replacement ($12,000), HVAC system ($8,000), and plumbing work ($10,000). Using the 70% rule: ($175,000 × 0.70) − $30,000 = $92,500 maximum offer. This leaves you room to cover closing costs, holding costs, and profit or equity.
For owner-occupants (not investors), the formula can stretch slightly. If you plan to live in the home long-term and don't need immediate profit, you might offer up to 75–80% of ARV. The key is knowing your repair costs with precision. Vague estimates lead to overpaying.
| Scenario | ARV | Repairs | Max Offer (70% Rule) | Discount from ARV |
|---|---|---|---|---|
| Light rehab | $155,000 | $15,000 | $93,500 | 40% |
| Moderate rehab | $175,000 | $30,000 | $92,500 | 47% |
| Heavy rehab | $145,000 | $45,000 | $56,500 | 61% |
Middletown's median move-in-ready home price hovers around $169,900 as of mid-2026. As-is homes typically trade 20–35% below this median, placing typical as-is offers in the $110,000–$136,000 range depending on condition. However, financing constraints can push offers lower. If you're financing through conventional or FHA channels, lenders may require additional repairs before approval, which reduces your maximum offer further.
What Should You Inspect Before Buying an As-Is Home?
A thorough inspection is non-negotiable when buying as-is. Unlike move-in-ready purchases where minor defects are acceptable, as-is homes demand a detailed walkthrough. Here's a practical checklist for Middletown properties:
Roof & Exterior:
- Roof age and remaining life (shingles, flashing, gutters)
- Siding condition (wood rot, gaps, missing sections)
- Windows and doors (operation, seals, rot)
- Grading and drainage around the foundation
Foundation & Basement:
- Visible cracks (hairline vs. structural)
- Water stains, efflorescence, or active seepage
- Sump pump presence and condition
- Radon levels (Butler County is EPA Radon Zone 1 - testing is critical)
Plumbing:
- Water pressure and color (rust indicates galvanized pipes)
- Visible corrosion or leaks under sinks
- Toilet operation and wax ring condition
- Sewer line age and any known backups
Electrical:
- Panel type and amperage (60–100 amps is outdated; 200 amps is standard)
- Knob-and-tube wiring (fire hazard, must be replaced)
- GFCI outlets in bathrooms and kitchen
- Any visible burn marks or scorching
HVAC:
- Furnace and AC age (15+ years suggests replacement soon)
- Ductwork condition and insulation
- Thermostat operation
Structural & Safety:
- Sagging floors or ceilings
- Visible mold or mildew
- Lead paint disclosure (all Middletown homes built before 1978 require lead paint disclosure)
Typical Repair Costs in Butler County:
- Roof replacement: $8,500–$14,000
- HVAC system (furnace + AC): $5,000–$10,000
- Full plumbing repipe (galvanized to copper/PEX): $4,000–$15,000
- Foundation crack sealing: $3,000–$7,500
- Foundation underpinning: $10,000–$30,000+
- Radon mitigation system: $800–$2,500
When to Walk Away: If foundation repairs exceed $15,000, structural issues are extensive, or mold contamination is present, seriously reconsider. These problems compound quickly and can exceed your repair budget. If the seller refuses to disclose known issues or the disclosure form contains obvious omissions compared to your inspection, walk away - this signals potential fraud.
How Do You Finance an As-Is Home Purchase in Middletown?
Financing an as-is property is more restrictive than financing a move-in-ready home. Not all loan products work for distressed properties. Here's what's available:
| Loan Type | As-Is Eligible? | Key Details |
|---|---|---|
| Conventional (20% down) | No | Requires property to meet standard appraisal; most as-is homes fail |
| FHA (3.5% down) | No | Must meet HUD Minimum Property Standards; as-is homes with safety/structural issues fail appraisal |
| VA | No | Similar to FHA; requires property to meet VA standards |
| FHA 203(k) Standard | Yes | Finances purchase + renovation; $5,000 minimum repairs; requires HUD-approved consultant |
| FHA 203(k) Limited | Yes | Simpler version; caps renovation at $35,000; faster approval |
| Hard Money | Yes | 10–13% interest, 1–3 point origination fee; 6–18 month terms; fastest closing |
| Cash | Yes | No financing; closes in 14–21 days; strongest negotiating position |
FHA 203(k) Rehabilitation Loans are the primary government-backed option for as-is buyers in Middletown. These loans allow you to finance both the purchase price and renovation costs in a single mortgage. The Standard 203(k) requires a HUD-approved consultant to oversee repairs, adding time and cost but providing lender confidence. The Limited 203(k) is faster and simpler but caps renovations at $35,000. Both require a minimum $5,000 in repairs. As noted in resources on buying homes as-is, even an as-is home must meet a lender's minimum property standards - most mortgage lenders require the home to be safe, structurally sound, and habitable before approving financing.
Hard Money Loans are popular with investors buying as-is properties. A $100,000 hard money loan at 11% interest for 12 months costs $11,000 in interest alone - before renovation expenses. Origination fees (1–3 points) add another $1,000–$3,000. Hard money closes quickly (7–14 days) and doesn't require a perfect appraisal, making it ideal for distressed properties. The trade-off is high cost and short repayment terms.
Cash Purchases offer the strongest position. Cash buyers close in 14–21 days versus 45–90 days for financed purchases, giving you meaningful negotiating leverage - often 5–10% additional discount from the seller. If you have cash available, as-is properties become significantly more attractive.
Step-by-Step Process to Buy an As-Is Home in Middletown
Here's the sequential path from search to closing:
Step 1: Find Listings & Get Pre-Approved Search MLS listings filtered for "as-is" or distressed properties in Middletown ZIP codes 45042, 45043, and 45044. If financing, get pre-approved for a 203(k) loan or conventional mortgage before you start making offers. According to The Homebuying Process for First-Time Homebuyers, securing pre-approval early is essential - it clarifies your budget, strengthens your offer, and helps you move quickly when the right property appears. If paying cash, confirm funds are available.
Step 2: Conduct a Professional Inspection Hire a licensed home inspector to walk the property. Request a detailed written report covering all systems. Budget $300–$500 for the inspection. This is your due diligence period - use it to gather hard cost estimates for repairs.
Step 3: Verify Seller Disclosures & Title Request the completed Residential Property Disclosure Form from the seller's agent. Cross-reference it against your inspection findings. Search the Butler County Auditor's property records online to verify ownership, prior transfers, tax status, and any recorded liens or judgments.
Step 4: Get Repair Estimates Obtain written quotes from licensed contractors for all major repairs (roof, HVAC, plumbing, foundation). Use these estimates to calculate your maximum offer using the 70% rule.
Step 5: Submit an Offer Draft your purchase agreement. Include an inspection contingency if possible (though as-is sellers often resist this). Specify a due diligence period (typically 7–14 days) for final walkthrough and title review. Ohio law allows a buyer due diligence period to investigate the property and title - use it.
Step 6: Negotiate & Accept Sellers of as-is properties expect negotiation. Lead with your repair cost data. If you're paying cash, emphasize your quick close timeline. If financing, mention your pre-approval. Most as-is deals involve 2–3 rounds of back-and-forth.
Step 7: Close Ohio does not require an attorney at closing, but title companies handle the transaction. Closing costs for buyers average 2–3% of the purchase price (approximately $2,600–$3,900 on a $130,000 purchase). Cash buyers pay closer to 1.5–2% since they avoid lender fees. Closing typically takes 30–60 days for cash, 60–90 days for financed purchases. First-time buyers who need help covering these upfront costs should also explore local down payment assistance programs, which may offer non-repayable loans toward down payment and closing costs on home purchases - a resource that can meaningfully reduce out-of-pocket expenses at closing.
Timeline Estimate:
- Cash purchase: 30–45 days from offer to close
- Financed (conventional/203k): 60–90 days
- Hard money: 14–21 days to close (fastest option)
Finding Reliable Cash Buyers & Local Resources in Middletown
If you're considering selling an as-is property rather than buying one, or if you want to explore a quick cash offer as an alternative to traditional financing, local cash home buyers can provide a streamlined path. Companies like Millennium Cash Buyers specialize in purchasing properties in any condition - whether they need extensive repairs, have title issues, or are facing foreclosure. A cash buyer eliminates the need for repairs, inspections contingencies, or lengthy financing timelines, closing in as little as 14–21 days.
For buyers, understanding the cash buyer market also helps with pricing strategy. If you're negotiating with a seller, knowing that they could sell to a cash buyer for a quick close gives you context for your offer. If you're an investor, cash buyers represent both competition and potential exit strategies for your own rehab projects.
When evaluating any local provider - whether a cash buyer, lender, or contractor - verify licensing through the Ohio Division of Real Estate & Professional Licensing, check references, and request written estimates. Transparency and local reputation matter, especially in a market like Middletown where relationships and word-of-mouth carry weight.
Frequently Asked Questions About Buying As-Is Homes in Middletown
How much below asking price should I offer on an as-is home in Middletown?
Direct Answer: Use the 70% rule: offer no more than 70% of the after-repair value minus your estimated repair costs. On a $175,000 ARV home needing $30,000 in repairs, your maximum offer is approximately $92,500.
In Middletown's market, as-is homes typically sell for 20–35% below comparable move-in-ready properties. However, the discount depends on repair severity and local competition. If multiple buyers are bidding, the discount shrinks. If the property needs $50,000+ in work, expect to offer 40–50% below ARV. Always anchor your offer to documented repair estimates, not guesswork.
Can I use an FHA loan to buy an as-is home in Middletown?
Direct Answer: Standard FHA loans cannot be used on most as-is properties because they must meet HUD Minimum Property Standards. However, FHA 203(k) rehabilitation loans are specifically designed for as-is purchases and allow you to finance both acquisition and repairs.
The FHA 203(k) Standard version requires a HUD-approved consultant and a minimum $5,000 in repairs. The Limited 203(k) is simpler but caps renovations at $35,000. Both require the property to be structurally sound enough to occupy during renovation. If the foundation is severely compromised or the roof is actively leaking into living spaces, even 203(k) may not work. Contact a local lender experienced with 203(k) loans to evaluate your specific property.
Does buying as-is mean I cannot get a home inspection in Ohio?
Direct Answer: No. You can always hire a home inspector. However, as-is sellers often resist inspection contingencies in the purchase agreement, meaning you inspect at your own risk and cannot use inspection findings to renegotiate or walk away.
The distinction is important: you can inspect, but you typically cannot condition your offer on inspection results. This is why getting a pre-offer inspection is smart - you gather data before submitting your bid, then make an informed offer without contingencies. Some as-is sellers will negotiate a brief inspection contingency (3–7 days), so always ask.
What are the biggest risks of buying an as-is property in Middletown?
Direct Answer: The primary risks are underestimating repair costs, discovering hidden defects after closing, and overpaying relative to the true condition. Secondary risks include financing challenges, title issues, and contractor delays during renovation.
In Middletown specifically, watch for galvanized plumbing (common in pre-1970 homes), foundation movement due to clay-heavy soil, radon (Butler County is Zone 1), and lead paint (pre-1978 homes). Get multiple contractor estimates before offering. Verify the title is clear through the Butler County Auditor. If you're financing, confirm your lender will approve the property before submitting an offer. Never skip the inspection or assume the seller's disclosure is complete.
How long does it take to close on an as-is home in Middletown?
Direct Answer: Cash purchases close in 14–21 days. Financed purchases (conventional or 203(k)) close in 60–90 days. Hard money loans close in 7–14 days.
The timeline depends on your financing path and the complexity of title or repairs. Cash is fastest because there's no lender appraisal or underwriting. FHA 203(k) loans take longer because the lender requires a consultant review and detailed repair scope. If the property has title issues (liens, tax delinquency, probate complications), closing can extend 30+ days beyond the standard timeline. Plan for 60–90 days if financing; 30–45 days if paying cash.
Are as-is homes a good investment in Middletown right now?
Direct Answer: As-is homes can be solid investments if you buy at the right price and accurately estimate repairs. Middletown's median home price of approximately $169,900 and aging housing stock create opportunities for value-add investors.
The key is discipline: stick to the 70% rule, get multiple repair estimates, and factor in holding costs and closing expenses. If you can acquire a property at 50–60% of ARV and complete repairs for 20–25% of ARV, you'll build equity. However, if you overpay or repairs exceed estimates, returns evaporate quickly. Owner-occupants should buy as-is only if they have cash reserves for unexpected repairs and can tolerate living through renovation.
What repairs must a seller still disclose even when selling as-is in Ohio?
Direct Answer: Sellers must disclose all known material defects in 11 categories: roof, foundation/basement, electrical, plumbing, HVAC, water intrusion, environmental hazards, underground storage tanks, zoning violations, HOA status, and sewer/septic systems. An as-is clause does not eliminate this obligation.
If a seller knowingly conceals a defect - for example, failing to disclose active basement water intrusion or a failing furnace they know about - they expose themselves to fraud liability. As a buyer, compare the completed disclosure form against your inspection report. If major defects appear on your inspection but not on the disclosure, document this discrepancy and consider legal consultation before closing.
Next Steps: Get Started Buying As-Is in Middletown
Buying an as-is home in Middletown requires discipline, but it's an achievable path to homeownership or investment returns. Start by getting a professional inspection on any property you're seriously considering. Use the repair estimates to calculate your maximum offer using the 70% rule. Verify the seller's disclosures and the title through the Butler County Auditor. If you're financing, confirm pre-approval for a 203(k) or hard money loan before submitting an offer.
If you're exploring a quick sale of an as-is property instead - whether due to inheritance, relocation, or financial pressure - cash buyers like Millennium Cash Buyers offer a streamlined alternative to traditional listing. They close quickly and handle properties in any condition, eliminating the need for repairs or lengthy marketing.
For questions about your specific property or to discuss financing options, reach out to a local lender or real estate professional. The Middletown market rewards informed buyers who do their homework upfront.
Ready to Get Started?
For personalized guidance, visit Millennium Cash Buyers to learn how we can help.
Frequently asked questions
What Does "As-Is" Actually Mean When Buying a Home?
When you buy an as-is home in Middletown, you're purchasing the property exactly as it stands - roof leaks, outdated plumbing, foundation cracks, and all. The seller makes no repairs and offers no warranties on the condition of the structure or systems. However, "as-is" does not mean the seller can hide problems or lie about what they know.
Why Are As-Is Homes Common in Middletown?
Middletown's housing stock is among the oldest in Butler County. (Ohio.gov) (Census.gov) According to the U.S. Census Bureau's 2023 American Community Survey, the median housing unit in Middletown was built in 1958 - meaning most homes are 66+ years old. Approximately 18.4% of the city's housing units were built in 1939 or earlier. This age profile creates a natural supply of properties with aging systems: galvanized plumbing, original electrical panels, roofs past their useful life, and foundat
How Much Should You Pay for an As-Is Home in Middletown?
Pricing an as-is home requires a disciplined formula. The most widely used approach among investors is the 70% rule: Maximum Allowable Offer = (After-Repair Value × 0.70) − Estimated Repairs. This ensures you build in enough margin for profit (if you're an investor) or equity cushion (if you're an owner-occupant).
What Should You Inspect Before Buying an As-Is Home?
A thorough inspection is non-negotiable when buying as-is. Unlike move-in-ready purchases where minor defects are acceptable, as-is homes demand a detailed walkthrough. Here's a practical checklist for Middletown properties:
How Do You Finance an As-Is Home Purchase in Middletown?
Financing an as-is property is more restrictive than financing a move-in-ready home. Not all loan products work for distressed properties. Here's what's available:
How much below asking price should I offer on an as-is home in Middletown?
Use the 70% rule: offer no more than 70% of the after-repair value minus your estimated repair costs. On a $175,000 ARV home needing $30,000 in repairs, your maximum offer is approximately $92,500.
Can I use an FHA loan to buy an as-is home in Middletown?
Standard FHA loans cannot be used on most as-is properties because they must meet HUD Minimum Property Standards. However, FHA 203(k) rehabilitation loans are specifically designed for as-is purchases and allow you to finance both acquisition and repairs.
Does buying as-is mean I cannot get a home inspection in Ohio?
No. You can always hire a home inspector. However, as-is sellers often resist inspection contingencies in the purchase agreement, meaning you inspect at your own risk and cannot use inspection findings to renegotiate or walk away.
What are the biggest risks of buying an as-is property in Middletown?
The primary risks are underestimating repair costs, discovering hidden defects after closing, and overpaying relative to the true condition. Secondary risks include financing challenges, title issues, and contractor delays during renovation.
How long does it take to close on an as-is home in Middletown?
Cash purchases close in 14–21 days. Financed purchases (conventional or 203(k)) close in 60–90 days. Hard money loans close in 7–14 days.